Minnesota Diminished Value Attorney for Repaired Vehicles
Minnesota’s no-fault benefits cover injury-related losses. Damage to your vehicle is a different claim, made against the at-fault driver’s liability coverage, and that is where a diminished value claim goes. A Minnesota diminished value attorney can build that claim with real evidence. Minnesota allows six years to sue for injuring personal property.
Minnesota key facts
six years to sue for injuring personal property. Carriers usually want notice far sooner.
the at-fault driver’s liability coverage. Your no-fault (PIP) benefits are for injury-related losses.
you can recover if your fault is not greater than the other party’s. Your award is reduced by your share.
Minnesota’s conciliation court hears claims up to $20,000.
612-383-1377, Monday to Friday, 8 AM to 5 PM. Weekends by appointment.
Minnesota is a no-fault state. Why can I still claim diminished value?
Because Minnesota’s no-fault system is about injuries. Your personal injury protection, or PIP, covers injury-related losses. Your vehicle’s value is a separate matter.
Vehicle damage is claimed against the at-fault driver’s liability coverage. A diminished value claim goes there too, as a third-party claim against that insurer. Drivers mix up the two systems all the time, and some adjusters are perfectly content to let the confusion stand.
What makes a repaired vehicle worth less?
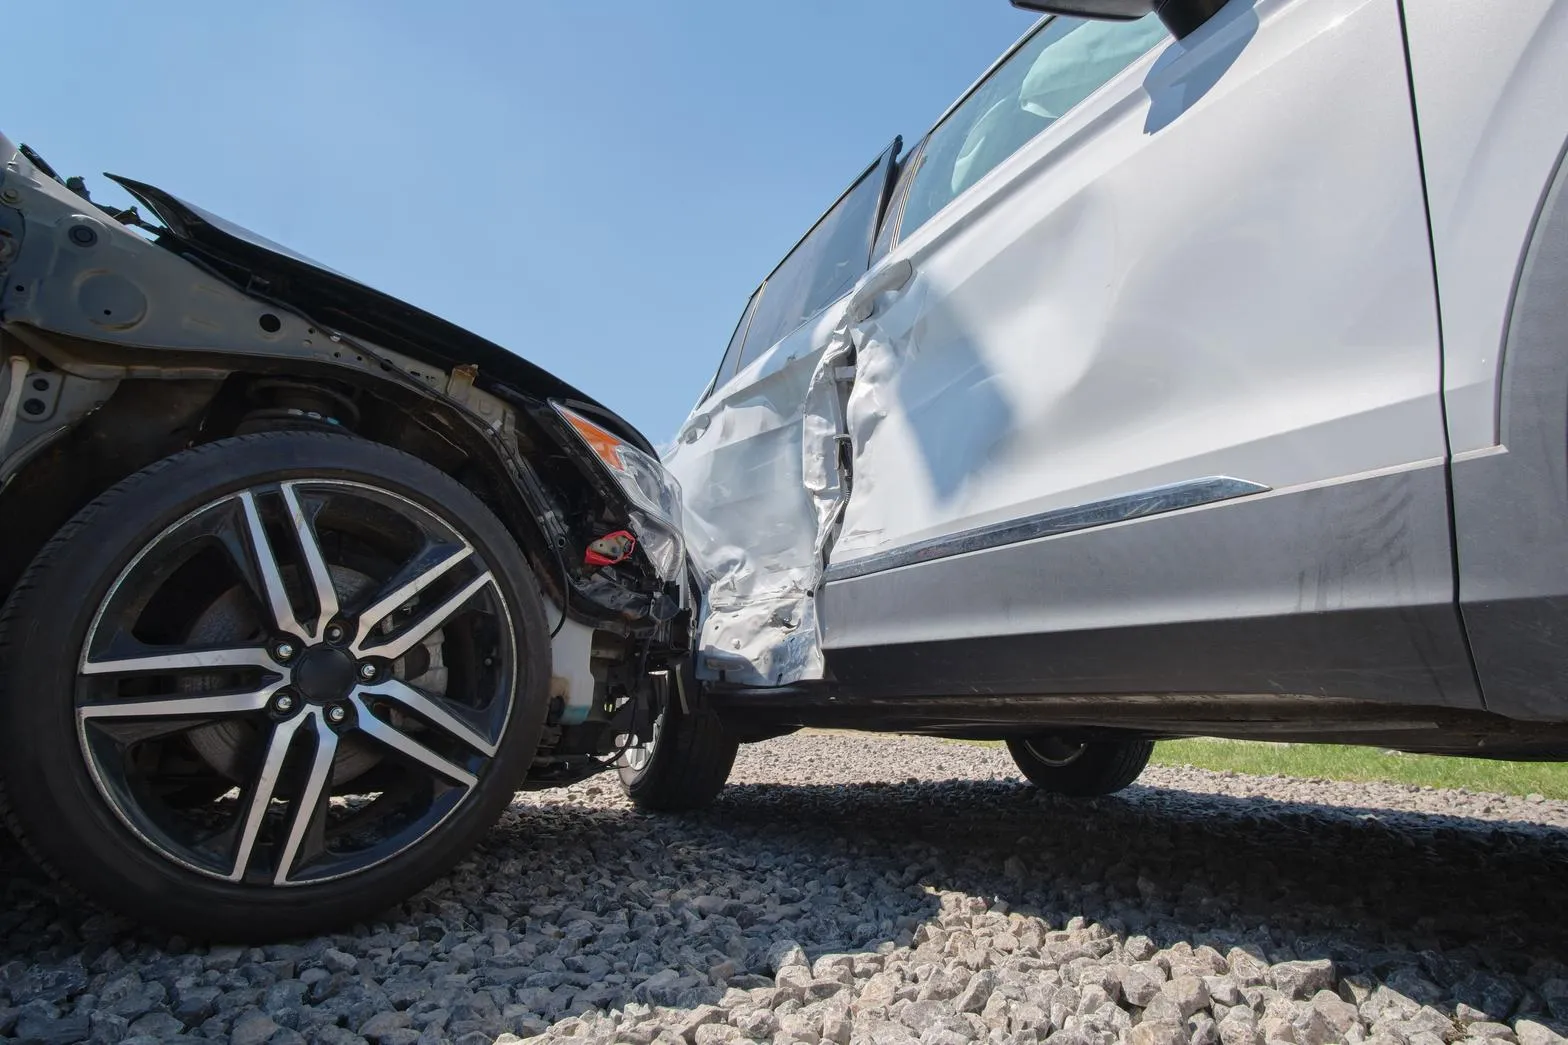
Picture two identical SUVs on a dealer lot in Bloomington. Same year, same trim, same miles. One has a clean Carfax. The other shows a reported front-end collision. Buyers pay less for the second one, and the dealer’s trade-in offer reflects that before anyone looks at the paint.
Once accurate accident history is on the report, it generally stays. Under the paint, a careful inspector can spot what the repair left behind: body filler, pinhole welds, hammer dimples, and heat-affected metal. Newer, low-mileage vehicles take the biggest hit in dollars, and so do luxury, performance, and specialty models and higher-value trucks and SUVs. You do not need to sell to have the loss. It exists the moment the value drops. Our diminished value claims overview covers the basics.
How long do I have to file a diminished value claim in Minnesota?
Minnesota allows six years to sue for injuring personal property. Treat that as the outer edge of the law. Planning around it is a mistake.
Insurers commonly set their own notice timelines, and those run shorter than the statute. Evidence has a shelf life too. Repair invoices, photos, and market comparables from right after the repair make the strongest case, and a claim built two winters later is harder to prove. Call while the details are fresh.
What if I was partly at fault?
You can still recover in Minnesota as long as your fault is not greater than the fault of the party you claim against. Whatever share of fault is assigned to you comes off the award. Be found more at fault than the other driver, and the claim is gone.
Winter claims are where this bites. Adjusters sometimes treat an icy-road crash as shared fault by default. Ice on the road is a fact about the weather, and we push back on any fault split the evidence does not support.
Can I claim diminished value from my own insurer?
Often not. Many personal auto policies do not pay diminished value on first-party collision claims, though the wording varies from one policy to the next. The main route is the third-party claim against the at-fault driver’s insurer. If your own carrier paid for the repair, the claim against the other driver’s carrier is still a separate claim.
Can I take a diminished value claim to conciliation court?
If the amount fits, it is an option. Minnesota’s conciliation court handles claims up to $20,000. For a larger claim, the options include district court, such as Hennepin County District Court in Minneapolis or Ramsey County District Court in St. Paul.
Court comes later, if at all. The claim starts with the carrier, and carriers respond to evidence far more than to frustration. When a carrier still will not pay, a Minnesota diminished value attorney can lay out your options, including which court fits your numbers.
Mistakes that can shrink a Minnesota claim
Most diminished value claims don’t fall apart on the law. They lose value through small decisions made in the first few weeks after the crash. The ones we see most often:
- Signing a property damage release that settles “all claims” for the vehicle before the lost value is addressed
- Giving a recorded statement to the other driver’s insurer that guesses at speed, distance, or road conditions
- Letting the shop skip pre-repair photos or discard replaced parts before anyone documents them
- Waiting until trade-in day to learn what the accident cost, when the crash details are harder to reconstruct
- Taking an adjuster’s word that Minnesota’s no-fault system covers the vehicle’s lost value
Each of these is easy to avoid if you know about it early. A short call before you sign anything or give a statement can protect thousands of dollars.
What if my vehicle is leased or financed?
A loan or lease doesn’t automatically stop you from bringing a diminished value claim, but it can change who receives the payment and what paperwork the insurer asks for. Lease agreements also differ on who owns a lost value recovery and whether you could face extra charges when you turn the vehicle in. Bring a copy of your lease or loan agreement to the free evaluation and we’ll walk through how it affects your claim.
How the 17c formula shortchanges Minnesota drivers
Many adjusters calculate diminished value with the 17c formula, which came out of a 2001 Georgia case. First it caps the base loss at 10% of pre-loss value. Next comes a damage modifier running from 1.00 for severe structural damage down to 0.00 for no structural damage. Last, it multiplies again by a mileage modifier that falls from 1.0 at zero miles to 0.0 at 100,000 miles or more.
Consider an illustrative vehicle with a clean-history market value of $28,000 that sells for $22,500 after repairs, a $5,500 loss. Run it through 17c: start with 10% of the $28,000, cut that in half for moderate damage, then multiply by 0.6 for 40,000 miles. What comes out is a small fraction of the $5,500 the market took. Nowhere does the formula ask what buyers actually pay. We do.
How a Minnesota diminished value attorney handles your claim
- Tell us about the vehicle. Year, make, model, mileage, and what happened.
- We evaluate the claim. You get a straight answer about what it is worth and if it makes sense to pursue.
- We build the evidence. Valuation work, repair documentation, and market comparables.
- We handle the carrier. The adjuster deals with us, not you.
- You recover the value. If the carrier refuses, we discuss your legal options.
An appraisal service sells a report and leaves you to argue with the adjuster. We stay with the claim beginning to end. Chris Johnston started this practice after years of watching carriers tell people they had no diminished value claim when they did. Chris Martineau worked in the property claims department of a major insurance carrier before becoming a trial attorney, and he holds licensure in multiple states.
Minnesota cities we serve
In the Twin Cities, we serve Minneapolis, St. Paul, Bloomington, Edina, Minnetonka, Plymouth, Eden Prairie, Maple Grove, Woodbury, and Eagan. Beyond the metro, we serve Rochester, Duluth, and St. Cloud. For local roads, courts, and questions, see our Minneapolis diminished value page and our St. Paul diminished value page. Other states are on our Locations page.
Minnesota diminished value FAQs
Call our Minnesota line
Call 612-383-1377, Monday to Friday, 8 AM to 5 PM, or request a free claim evaluation. Tell us the year, make, model, mileage, and what happened, and one of our attorneys will review it.