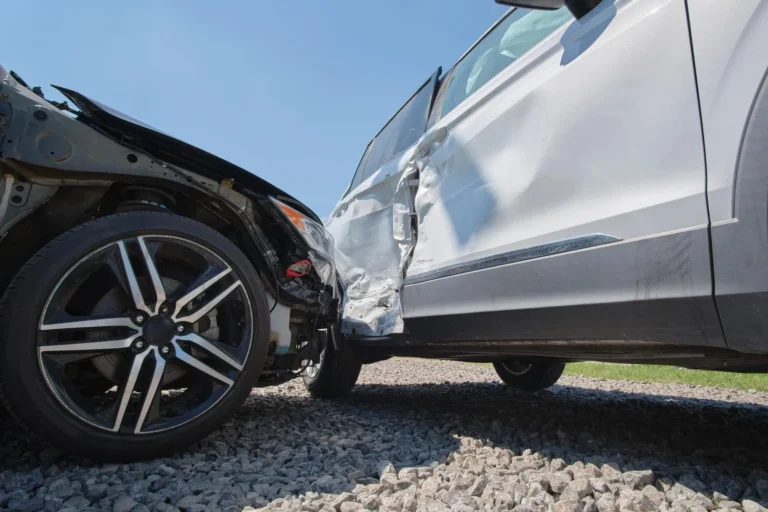
If you’ve put real money into a vehicle, a crash costs you more than the repair bill shows. A good shop can make the car look new again. It can’t take the accident off the car’s history, and the more the car is worth, the more that history costs you.
Same accident, very different loss
Diminished value is the drop in a car’s resale value because it now has an accident on its record, even after quality repairs. Buyers pay less for a car that’s been wrecked. That’s true for every vehicle on the road.
What changes is the size of the hit. Picture two cars with the same repair. One is an $18,000 commuter sedan. The other is a $72,000 SUV that’s two years old. Even if both lost the same 15% at resale (a hypothetical, to show the scale), the sedan owner is out $2,700. The SUV owner is out $10,800.
That’s a real number on a trade-in or a private sale. And it’s money the at-fault driver’s insurance company rarely brings up on its own.
Why higher-end buyers are less forgiving
They have options. Someone shopping for a $70,000 vehicle can usually find a comparable one with a clean history. They don’t have to take a chance on yours, so they either pass or offer less.
They check. History reports show up on nearly every dealer listing, and buyers at this price point read them closely.
Certified pre-owned matters. Many manufacturer certified pre-owned programs have inspection and history standards. A car with significant accident damage may not qualify, which can cut it off from the part of the used market that pays the most.
The engineering is more complicated. Aluminum body panels, cameras, radar sensors, and driver assist systems often need special repair procedures and recalibration. Buyers know that, and they worry about whether it was done right.
The loss shows up sooner. Owners of newer vehicles often trade in or sell within a few years. That means diminished value isn’t a someday problem. It’s a number you’ll likely see at the dealership.
The “it looks perfect” trap
A great repair is not the same as no loss. Plenty of owners never file a diminished value claim because the car looks and drives fine. The insurance company is happy to let that happen.
The loss isn’t visible in your driveway. It shows up the day a dealer or buyer runs the VIN.
Signs you may have a strong claim
Every case is different, but these tend to point toward a claim worth looking at:
- The accident wasn’t your fault
- The vehicle was newer and in good shape before the crash
- The repairs were significant, especially frame, unibody, or other structural work
- The accident is on, or will end up on, a vehicle history report
- The vehicle is higher value or in high demand
You don’t have to check every box. The details of your car and your repairs matter more than any one item on a list.
What to do now
- Keep everything. Repair estimates, the final invoice, photos, the police report, and every message from the insurance company.
- Read any release before you sign it. Ask whether it covers diminished value. Don’t assume it doesn’t.
- Get a number based on your car. Insurers often use a generic formula that keeps offers low.
- Watch the deadline. Each state sets its own time limit for filing.
Talk to Diminished Value Attorneys
Our attorneys handle diminished value claims for vehicle owners in Iowa, Minnesota, Wisconsin, and Texas. If your car was wrecked and repaired, let us take a look at what it’s really worth now.
Iowa: 515-337-9760 | Minnesota: 612-383-1377 | Wisconsin: 414-401-7320 | Texas: 972-338-4070
This post is for general information only and is not legal advice.
-

The Diminished Value Attorneys Skilled Trades Scholarship
There’s an old saying that a lot of folks in crisp, white-collar offices have forgotten: Work is not a four-letter word. Every single day, millions of people get up, put on boots, and do the heavy lifting that keeps this country moving. They are the mechanics, the technicians, and the artisans of the skilled trades…. -
Why Your Diminished Value Offer Is So Low
You did everything right. The car went to a good shop, the paint matches, and it drives the way it did before. Then you asked the other driver’s insurance company about diminished value, and the number they came back with barely covers a car payment. That number probably didn’t come from looking at your car. It came from a formula.